
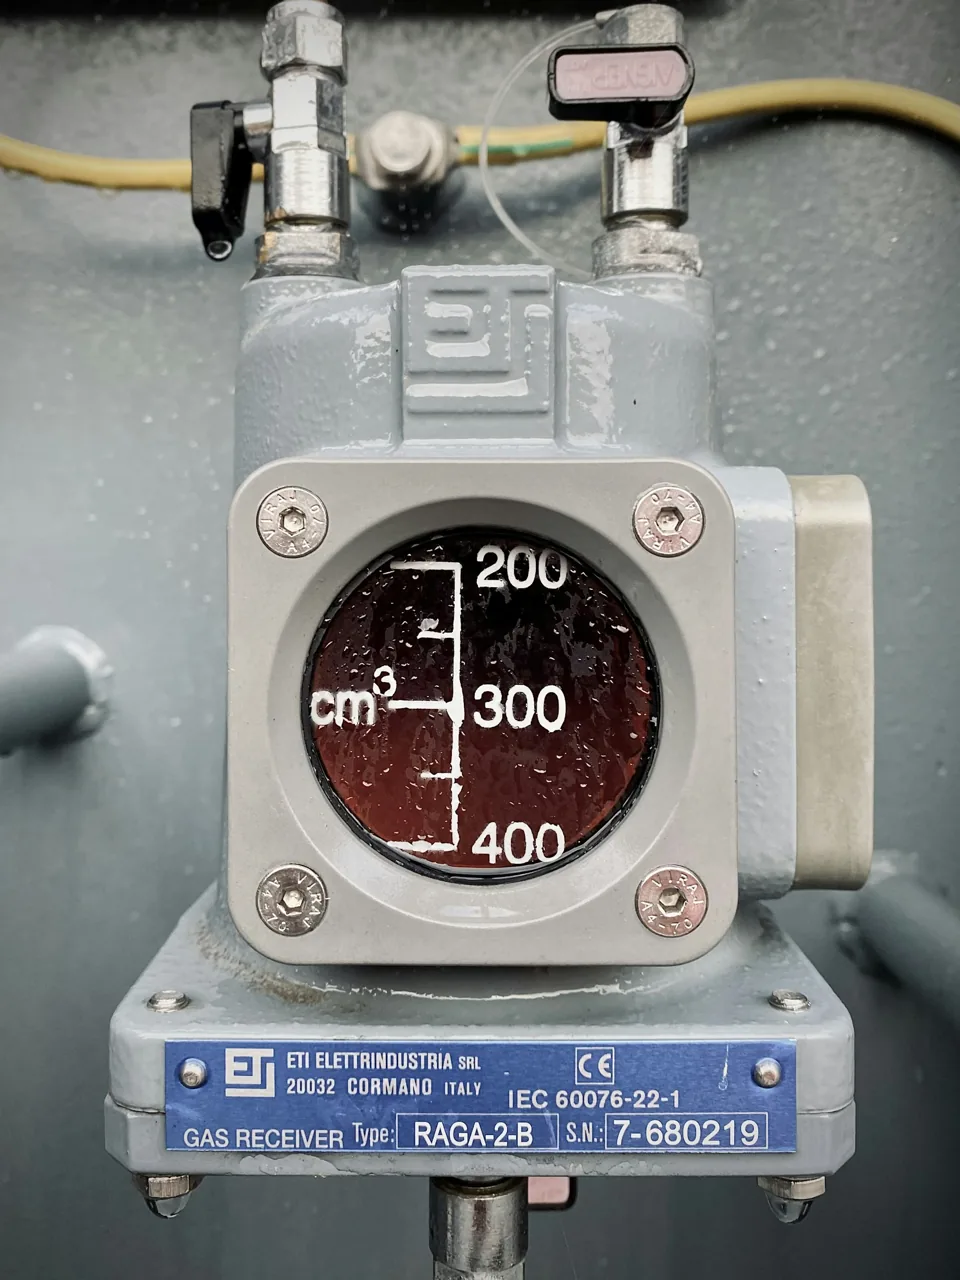
FOR Independent electrical testing firms, commissioning specialists and diagnostic laboratories
The test method defines the service
An electrical testing firm may perform insulation testing, relay evaluation, transformer diagnostics or acceptance testing. Describe each service and the equipment involved rather than submitting a single electrical-contractor classification. Separate observation and reporting from setting protective devices, modifying equipment or authorizing energization. Those distinctions affect both contractual responsibility and the insurance review.
OSHA’s electric-power framework distinguishes particular high-voltage and high-power testing from routine measurements. Safety professionals must determine the applicable requirements for the actual work. The insurance submission should explain qualifications, procedures and supervision without implying that an insurance policy certifies a test method or replaces the client’s operating controls.
Technical error and physical damage can overlap
Consider a test setup that damages a transformer, or an incorrect report that leads a customer to energize defective equipment. The first event may raise questions about damage to property being worked on; the second may involve reliance on professional services. Review general liability and professional liability together, including their definitions, exclusions and any gaps between them.
Examine limitations for faulty workmanship, impaired property, loss of use and contractual performance guarantees. A promise that equipment is fit for unrestricted service can be broader than an obligation to perform a defined test competently. Identify who interprets results and who makes the final operational decision before agreeing to the deliverable.
Protect the instruments and the evidence
Test sets, diagnostic instruments and temporary leads move among customer locations and may be exposed during loading, setup or overnight storage. Review owned and rented equipment values, transit arrangements and calibration-related downtime. The cost of replacing an instrument is different from the cost of repeating customer tests whose reliability is later questioned.
After an alleged error, preserve the original readings, instrument identifiers, calibration records, settings, photographs and report revisions. A retest can alter the evidence, so coordinate investigation and notifications before destructive examination or disposal. Record the customer’s equipment condition and instructions; an existing defect may be important to both causation and responsibility.
Contract scope should match the report
Useful underwriting material includes a service matrix, sample reports, contract terms, staff credentials, quality reviews and loss history. Explain whether the firm provides engineering opinions, performs switching or employs subcontractors. Identify work at generation plants, substations, industrial facilities and other locations where a small error can interrupt a much larger operation.
Review professional-liability continuity, retroactive dates and reporting obligations when changing insurers or buying another testing firm. Clarify ownership of historic reports and responsibility for responding to later claims. A carefully bounded report should state the tests performed, conditions observed and limitations, while the insurance program is reviewed against the actual services rather than an overly narrow trade description.
Operational exposures & coverage review
These review points are educational interpretation, not promises of insurance coverage.
| Exposure | Insurance review |
|---|---|
| Customer equipment damage | Review property-being-worked-on and care/custody limitations. |
| Incorrect technical report | Examine professional services and reliance provisions. |
| Testing equipment | Schedule mobile instruments and rented test sets. |
Questions for your next review
- Who authorizes energization after testing?
- Do liability forms address both hands-on testing and professional conclusions?
- Are original readings and calibration records retained?
Related Montridge webinars
Utility contractor insurance requirements relevant to testing engagements.
Energy operations
Utility Contractor Insurance Requirements Checklist | Protect Your Projects & Contracts
Clicking Load video connects to YouTube. No player loads automatically.
Watch on YouTube ↗Connect this topic to your program
Bring the operational details above into a coordinated review of your contracts, loss history and actual policy wording. Explore Montridge power & utility contractor insurance services for the related brokerage service.
Source references
Primary-source background informs the technical discussion. Insurance review questions are educational interpretation; a source link does not establish coverage or certify compliance.
OSHA federal electric-power operations and maintenance scope; applicability depends on the work.
Scope: United States; technical background and applicable federal framework · Source reviewed 2026-11-01
Federal construction standard addresses underground electrical installations, including cable identification and vault work.
Scope: United States; technical background and applicable federal framework · Source reviewed 2026-11-01
Prepared November 1, 2026. Confirm current requirements and their application to your work before relying on them. Specific insurance outcomes require review of the complete policy and endorsements.