
FOR Energy developers, EPC contractors, lenders, and project managers
Map the project from delivery to operation
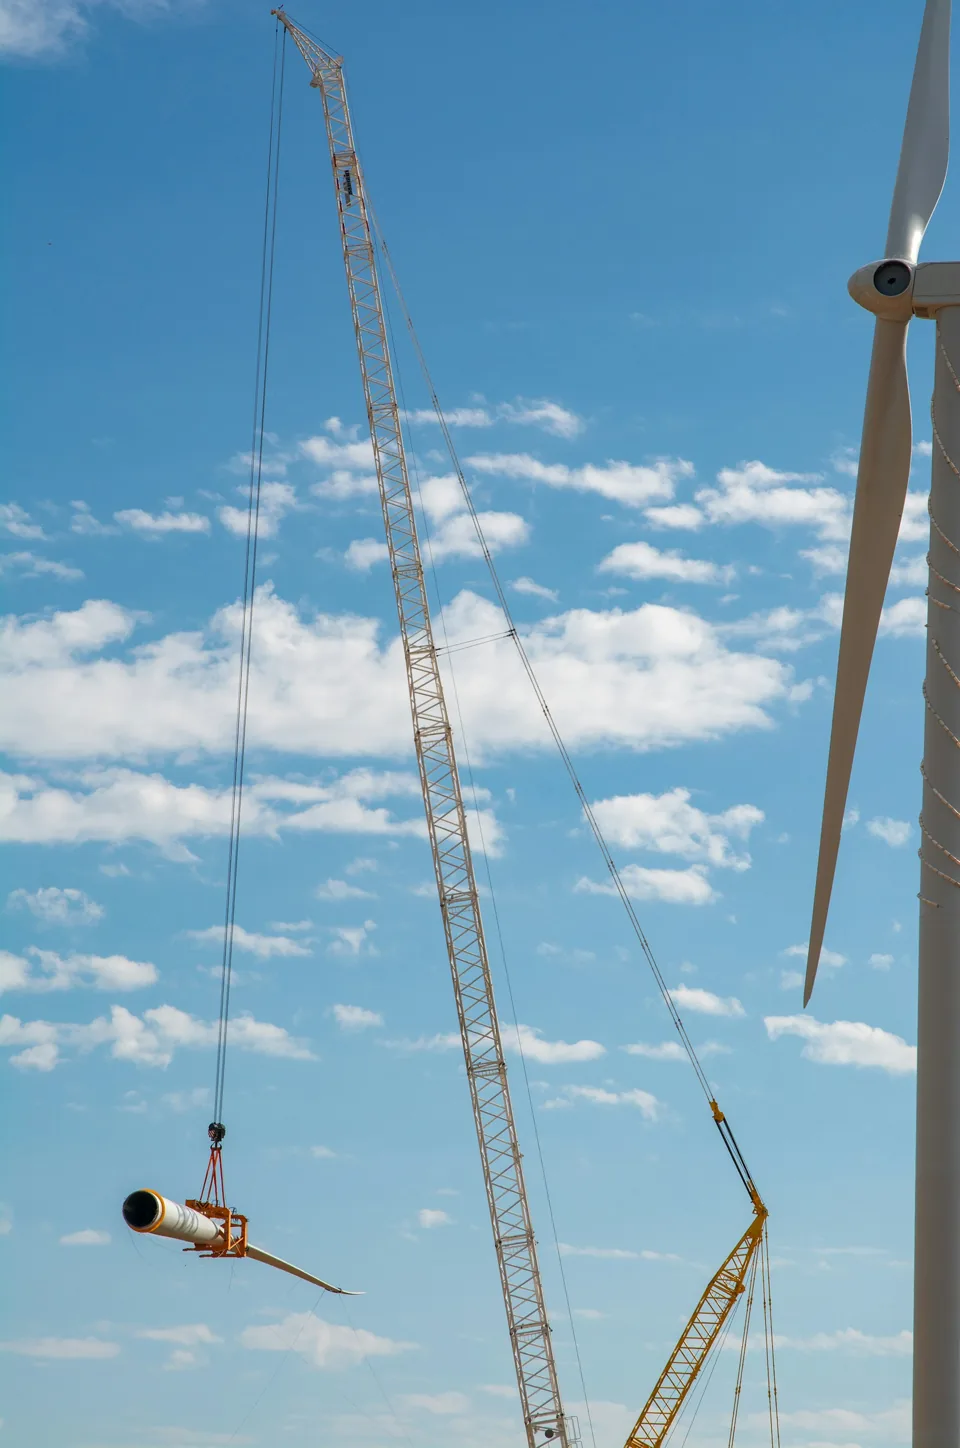
An energy project moves through fabrication, transit, storage, erection, testing, commissioning, and handover. Insurance responsibilities may change at each stage. Prepare a milestone map showing ownership, custody, contract responsibility, and the intended placement for each phase.
Include owner-supplied equipment and items fabricated away from the project site. Battery units, turbines, transformers, and pressure vessels may have values and delivery dependencies that differ from ordinary building materials. Review temporary works, existing property, and adjacent operating assets separately rather than assuming they form part of the new project’s insured value.
Review testing and defect provisions closely
Testing and commissioning can introduce hazards that do not exist during erection. Ask how the form addresses cold testing, hot testing, energization, mechanical operation, and introduction of feedstock. Confirm the transition to operational insurance and the effect of partial handover or early use.
Review exclusions and any applicable provisions for defective design, materials, or workmanship. The distinction between correcting a defect and resulting damage is important but depends on the actual wording. Avoid describing a project policy as covering all construction defects or every failure discovered during startup.
Separate physical damage from project delay
A delay in startup review should identify the required insured damage trigger, the scheduled commencement date, waiting periods, limits, and the method of measuring financial loss. Delay caused solely by financing, permitting, labor availability, or an undamaged supplier may fall outside the intended arrangement.
Build the financial model around the critical path and realistic replacement lead times. Consider interest, fixed costs, contracted revenue, and other project economics with the project’s advisers. Compare the schedule assumptions used by the insurance team with those maintained by the EPC and project controls teams.
Control changes before they become disputes
Maintain change orders, updated values, schedule revisions, inspection records, and commissioning procedures. Identify who must notify insurers when milestones shift, testing is extended, or completed portions begin operating. Review subcontractor responsibilities and deductibles before an incident creates competing interpretations.
At handover, reconcile the construction placement with operational property, breakdown, liability, and income arrangements. Keep acceptance certificates and outstanding punch-list items clear. The objective is an orderly transition with documented responsibilities, not an assumption that one policy automatically continues until every commercial objective of the project has been achieved.
For imported equipment, examine the link between marine cargo insurance and the construction placement. Damage discovered on arrival may have occurred at several possible stages. Retain inspection, packaging, transport, and acceptance records, and confirm notice procedures across the relevant policies. These records can help establish chronology without presuming which insurer ultimately owes a response.
Questions for your next review
- Who insures equipment during fabrication, transit, and storage?
- How are testing and partial operation treated?
- What insured event must cause a delay-in-startup loss?
Related Montridge webinars
EPC, contracts and commercial coverage
Builder's Risk Insurance Explained: What Every Contractor, Developer & Property Owner Should Know
Clicking Load video connects to YouTube. No player loads automatically.
Watch on YouTube ↗
EPC, contracts and commercial coverage
Delay in Startup (DSU) Insurance Explained | Builder's Risk, Infrastructure & Project Management
Clicking Load video connects to YouTube. No player loads automatically.
Watch on YouTube ↗Connect this topic to your program
Bring the operational details above into a coordinated review of your contracts, loss history and actual policy wording. Explore Montridge EPC insurance services for the related brokerage service.
Source references
Primary-source background informs the technical discussion. Insurance review questions are educational interpretation; a source link does not establish coverage or certify compliance.
Prepared November 1, 2026. Confirm current requirements and their application to your work before relying on them. Specific insurance outcomes require review of the complete policy and endorsements.