
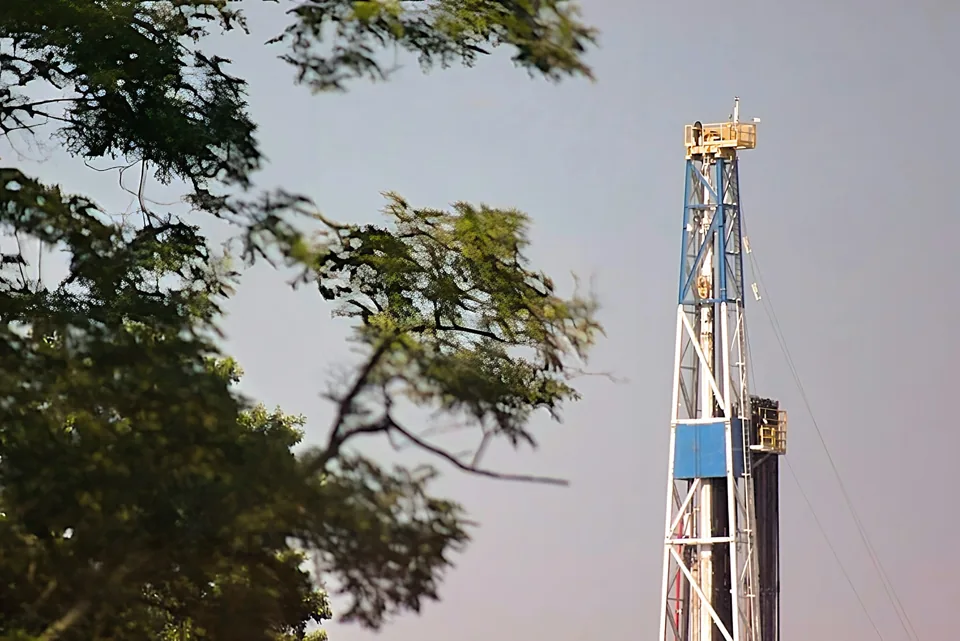
FOR Well servicing, workover, and intervention contractors
Define the intervention precisely
Well servicing can range from routine maintenance to an intervention that materially changes the condition of an existing well. Describe the services performed, equipment used, pressure environment, and whether the well remains live during any part of the work. A general service-contractor classification may not communicate the full operation.
Identify who plans the intervention, approves changes, controls the well, and directs subcontractors. Document the handoff between the operator and service crew. These details matter when evaluating responsibility for an event, particularly where the contractor’s equipment is connected to customer facilities or another service company’s pressure system.
Examine damage to the well and equipment
A service contractor can face allegations involving damaged customer property, lost tools, unsuccessful work, and loss of production. These allegations do not necessarily fit the same coverage section. Review property being worked on, underground resources, well damage, professional services, and contractual assumptions against the actual policy wording.
Inventory owned and rented service rigs, pumps, tools, and ancillary equipment. Establish how property is valued and whether transit, temporary storage, and equipment leased from others are addressed. Ask specifically about retrieval costs and equipment below the surface; do not infer their treatment from the presence of contractors equipment insurance.
Explain control of pressure and job changes
The underwriting narrative should show how jobs are planned and how crews respond when actual conditions differ from the work program. Include relevant pressure-testing, equipment inspection, maintenance, and competency practices. Describe how responsibilities are communicated when several employers work together at one wellsite.
OSHA guidance identifies pressure equipment and hazardous energy among oilfield safety concerns. The contractor should determine applicable procedures with qualified safety personnel. From an insurance perspective, evidence that the operation is accurately described and managed is more useful than a generic statement that every job follows industry best practices.
Check indemnity before mobilization
Review master service agreements and work orders together. A work order may add obligations that are not obvious in the standard agreement, including responsibility for customer equipment or extended downtime. Have counsel assess the legal allocation and the broker compare the insurance requirements with the proposed program.
Prepare loss history, payroll by activity, equipment schedules, and a description of higher-hazard services. Flag any expansion into new intervention methods before work begins. The desired outcome is a documented understanding of insured exposures, retained obligations, and conditions that require additional underwriting review.
A useful job-level review distinguishes the original work instruction from additional services requested in the field. Record who approved the additional task and whether it changes the equipment, pressure exposure, or contractual responsibility. The insurance implications of expanded intervention work should be considered before it becomes a routine practice that is absent from the company’s declared operations and renewal submission.
Questions for your next review
- Does the submission identify live-well intervention work?
- How are damage to the well and downhole equipment treated?
- Who authorizes a change from the original work program?
Related Montridge webinars
Energy operations
Heavy Equipment Insurance for Energy Contractors: What You Should Know
Clicking Load video connects to YouTube. No player loads automatically.
Watch on YouTube ↗
EPC, contracts and commercial coverage
What Insurance Do Oil & Gas Contractors Need? (Full Breakdown)
Clicking Load video connects to YouTube. No player loads automatically.
Watch on YouTube ↗Connect this topic to your program
Bring the operational details above into a coordinated review of your contracts, loss history and actual policy wording. Explore Montridge energy services insurance services for the related brokerage service.
Source references
Primary-source background informs the technical discussion. Insurance review questions are educational interpretation; a source link does not establish coverage or certify compliance.
Prepared November 1, 2026. Confirm current requirements and their application to your work before relying on them. Specific insurance outcomes require review of the complete policy and endorsements.